
Dear Catonsville Gateway Homeowners, Board Members, and Management,
In my August 11 Director’s Update, Do You Know How Your Condo Fees Are Being Spent?, I raised concerns about the Association’s financial oversight, unexplained invoice discrepancies, and the difficulties I experienced obtaining answers and supporting records.
I asked a straightforward question:
If an elected Director identifies financial discrepancies and cannot obtain answers, who is ensuring that homeowners’ assessment dollars are being properly reviewed?
Two months later, I find myself asking that question again. This time, it concerns the Association’s proposed 2027 budget and the process by which it was reviewed and distributed to homeowners.
I am providing this update in my individual capacity as an elected Director and homeowner, not on behalf of the Board of Directors as a whole.
Your Elected Board of Directors
For reference, the current Catonsville Gateway Board of Directors consists of:
- Patsy Paster — President
- Melody Lombardo — Treasurer
- Jaria Howard — Vice President
- Eugena Nurse — Member at Large
- Terry White — Director
As elected directors, we share responsibility for overseeing the Association’s operations, finances, and governance. Accountability applies to all five of us, regardless of our individual positions.
The August 3 Board Meeting — Financial Concerns Raised
During the August 3, 2026 Board meeting, I raised concerns regarding previously identified invoice discrepancies and the Association’s financial oversight practices.
As documented in my August 11 update, Board President Patsy Paster stated, to my recollection, that the invoice matter should be tabled until the next meeting.
I also made a motion that Association invoices be reviewed for accuracy as part of the Board’s financial oversight responsibilities. To my recollection, that motion was not put to a vote.
During that same meeting, Treasurer Melody Lombardo stated, to my recollection, that the Association was over budget on legal expenses.
I raised concerns about those expenditures and questioned how the Association’s legal costs were being managed and accounted for.
These were legitimate financial oversight questions raised during an official Board meeting by an elected director.
The invoice matter was deferred for future discussion, while questions concerning legal expenditures remained important as the Association approached its annual budgeting process.
The September 28 Board Meeting Was Canceled Without Explanation
On September 22, 2026, homeowners were notified that the regularly scheduled September 28 Board meeting had been canceled.
The cancellation notice provided no explanation for why the meeting was canceled and did not indicate whether or when it would be rescheduled.
On September 29, I submitted a written request to the Board seeking clarification regarding:
- The reason the September 28 meeting was canceled.
- Who made or authorized the decision to cancel the meeting.
- Whether the meeting would be rescheduled and when directors could expect notification.
I have not received a documented explanation addressing those questions.
This is particularly concerning because the August 3 discussion included an invoice matter that President Paster wanted deferred until the next meeting.
I do not know whether that issue would have appeared on the September 28 agenda. Nevertheless, canceling a scheduled meeting without explaining the cancellation or identifying a replacement date raises reasonable questions about how deferred Board business is handled.
When financial oversight questions are tabled for a future meeting, what process ensures those questions are eventually addressed?
September 25 — The Board President Raises Budget Concerns
On September 25, 2026, Community Manager Andrea Beaird distributed the draft 2027 budget to all five Board members for review and consideration.
Later that evening, Board President Patsy Paster responded with concerns involving insurance premiums, general legal expenses, the proposed 7% assessment increase, and grounds maintenance.
She concluded her email by stating:
“Board need to discuss all these increases.”
I agree that these expenditures warranted discussion.
However, I was not subsequently notified of or invited to any additional Board meeting or deliberation addressing those concerns.
October 16 — Homeowners Receive the Proposed Budget
On October 16, 2026, homeowners received the proposed 2027 budget accompanied by a notice stating that the Board had reviewed it.
The budget reflects a 7% assessment increase, bringing monthly condominium assessments to $293 per unit.
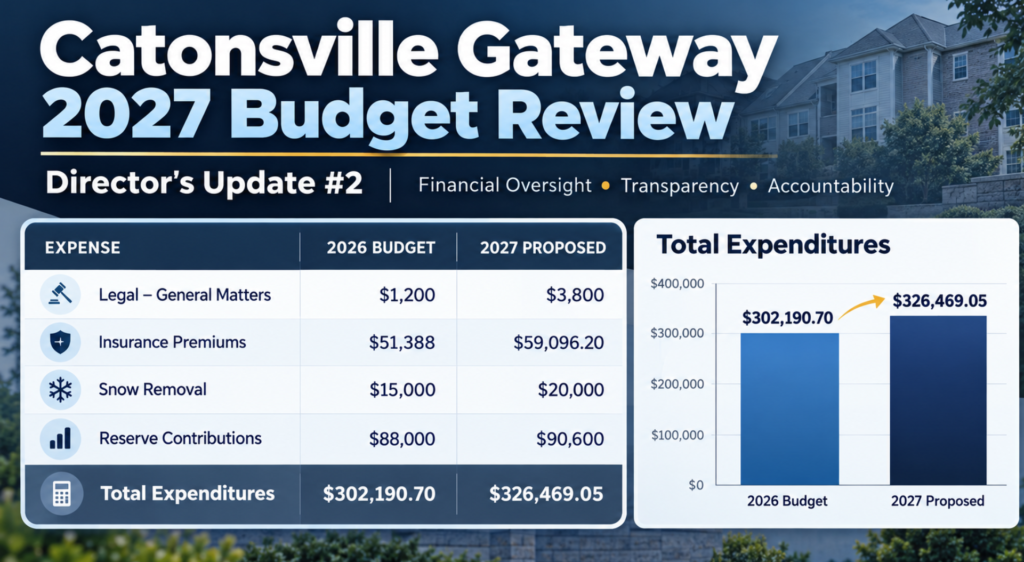
The Association’s total proposed annual expenditures increase from $302,190.70 in 2026 to $326,469.05 in 2027, approximately an 8% increase.
Some notable changes include:
| Expense | 2026 Budget | 2027 Proposed |
|---|---|---|
| Legal — General Matters | $1,200 | $3,800 |
| Insurance Premiums | $51,388 | $59,096.20 |
| Snow Removal | $15,000 | $20,000 |
| Reserve Contributions | $88,000 | $90,600 |
| Total Expenditures | $302,190.70 | $326,469.05 |
Increases may be justified by changing operating conditions, contractual obligations, or the Association’s financial needs.
But justification requires more than listing higher numbers. It requires supporting information and meaningful financial review.
As an elected and currently serving director, I received the September 25 draft budget and the October 16 homeowner notice. I was not involved in any subsequent Board discussion or decision authorizing its distribution, nor was any additional review or authorization process communicated to me.
I therefore do not know whether President Paster’s concerns were subsequently addressed, whether revisions were considered, or how the budget was finalized for distribution.
I am not alleging that an undisclosed meeting necessarily occurred. I am requesting documentation identifying what actually took place.
Legal Expenses — A Concern Raised Before This Budget
One expenditure deserves particular attention.
During the August 3 Board meeting, Treasurer Melody Lombardo stated, to my recollection, that the Association was over budget on legal expenses.
I raised concerns regarding those expenditures.
On September 25, President Paster also questioned the proposed legal budget, referencing $2,799.98 in her correspondence and questioning an increase to $3,800.
The proposed 2027 budget now increases the general legal-expense allocation from $1,200 to $3,800.
That is a 216.7% increase over the 2026 budgeted amount.
This raises several questions:
- What caused the Association’s legal expenditures to exceed the 2026 budget?
- What legal matters accounted for those expenditures?
- Who authorized the expenditures, and under what approval process?
- Did any of those costs arise from disputes involving Board governance or disagreements concerning directors’ responsibilities?
- What financial analysis supports increasing the 2027 general legal budget to $3,800?
I recognize that some legal communications and information may be protected by attorney-client privilege.
However, legitimate confidentiality considerations should not prevent appropriate financial oversight or disclosure of nonprivileged expenditure information.
The question is not simply whether legal fees were incurred. It is whether those expenditures were necessary, properly authorized, and in the Association’s financial interests.
Connecting This to Director’s Update #1
In my first update, I documented concerns involving a $2,400.26 repair invoice.
The documents available to me contained apparent discrepancies involving the estimate subtotal and exhaust fan charges. I also sought information establishing the underlying cause of the damage and the basis for the Association’s financial responsibility.
After submitting written questions, my request was escalated through management and subsequently closed pending further notice without the substantive answers I had requested.
As of August 11, 60 days had passed since my original inquiry.
Those questions concerned one Association expenditure.
The proposed 2027 budget concerns more than $326,000 in anticipated annual spending.
The amounts differ substantially, but the underlying principle is the same:
When an elected director raises reasonable questions about Association expenditures, there should be a transparent process for reviewing those questions, providing supporting information, and documenting decisions.
Questions for the Board and Management
To establish how the proposed budget was handled, I am formally requesting written clarification and the relevant existing records addressing the following:
Budget Review: Did any Board meetings, electronic discussions, or other deliberations concerning the proposed 2027 budget occur after September 25, 2026? If so, when and who participated?
Director Participation: If additional discussions occurred, how were all elected directors notified and afforded the opportunity to participate?
President’s Concerns: How were the financial concerns raised by President Paster on September 25 addressed before the proposed budget was distributed to homeowners?
Authorization: Who authorized distribution of the proposed 2027 budget, and what procedure was used to obtain that authorization?
Budget Approval: Has the Board formally approved any version of the 2027 budget, or does approval remain pending the Annual and Budget Adoption Meeting?
Meeting Cancellation: What is the status of my September 29 inquiry regarding the unexplained cancellation of the September 28 Board meeting? Who authorized the cancellation, and was a replacement meeting scheduled?
Deferred Financial Matters: What action, if any, was taken regarding the invoice review questions deferred during the August 3 meeting?
Legal Expenditures: What nonprivileged financial documentation supports the 2026 legal-expense overrun and the proposed 2027 increase?
Supporting Financial Records: What budget-versus-actual reports, contracts, projections, and other financial records were relied upon in preparing and reviewing the proposed increases?
Please provide the relevant existing meeting notices, agendas, minutes, resolutions, budget revisions, and Board communications documenting these matters. Any confidential or privileged materials may be handled separately through appropriate director-access procedures.
I request a written response before the budget adoption meeting and ask that an appropriate nonconfidential explanation be made available to homeowners.
Accountability Should Not Be Optional
Every month, homeowners pay assessments with the expectation that those funds will be managed responsibly.
As elected directors, we share responsibility for overseeing those resources.
I recognize that an individual director cannot independently establish Board policy, compel a Board vote, or act on behalf of the Board as a whole.
However, a director can review records, question expenditures, request supporting documentation, make motions, and seek explanations concerning the Association’s financial decisions.
Those responsibilities require access to information and meaningful opportunities to participate in Board business.
In my August 11 update, I asked whether the Association’s financial records and expenditures were receiving the review homeowners should reasonably expect.
Now, after an unexplained meeting cancellation, previously raised financial concerns, and distribution of a proposed budget without a subsequent review process being communicated to me, I believe that question remains relevant.
Why should an elected director have to ask when and how the Board reviewed a budget that the Association represents as having been reviewed by the Board?
These questions are not intended to prevent necessary maintenance, delay legitimate expenditures, or create unnecessary conflict.
They concern the Board’s responsibility to manage community resources with transparency, sound financial judgment, and accountability.
A Final Thought for Homeowners
The Annual Meeting and Board elections are approaching.
This is an appropriate time for all of us to examine how our Association operates, how financial decisions are made, and whether our governance practices provide the transparency homeowners deserve.
I am not asking homeowners to accept my conclusions.
I encourage you to review the proposed budget, examine the documented correspondence, ask questions, and form your own assessments of how our community is being managed.
Accountability should apply to every Board member, including me.
I will continue reviewing available Association records, asking questions, and sharing documented information about issues affecting our community.
I also request that this correspondence be retained as part of the Association’s official records concerning the 2027 budget review.
Thank you for taking the time to remain informed and engaged in the management of our community.
Respectfully,
Terry White
Elected Director and Unit Owner
Catonsville Gateway Condominium
NeighborTerry.org
September_25_Draft_Budget_Correspondence_REDACTED-1.pdf
September_28_Meeting_Cancellation_Inquiry_REDACTED-1.pdf
